By David Lawder and Andrea Shalal
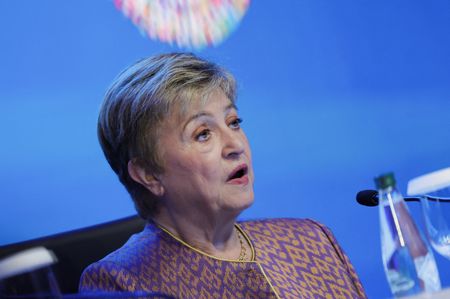
BANGKOK, Oct 14 (Reuters) – The United States cannot grow its way out of mounting public debt without tax or spending adjustments, while China must pivot from export-led growth towards more domestic consumption, International Monetary Fund Managing Director Kristalina Georgieva said on Wednesday.
Georgieva admonished the world’s two largest economies to make painful policy changes to reduce growing fiscal and trade imbalances, as her fiscal affairs chief said inflation, high debt levels and rising yields had heightened the urgency for budget consolidation around the globe.
Speaking at the IMF and World Bank annual meetings in Bangkok, Georgieva singled out advanced economies, namely the US and European countries, as the “worst offenders” on excessive debts, with higher benchmark yields spilling over to low-income countries that have already been forced by financial markets to rein in borrowing.
Asked at a press conference whether the US needs tighter fiscal policy, Georgieva said Treasury Secretary Scott Bessent recognizes that US deficit and debt levels are too high and need to be made more sustainable.
“The authorities very much rely on strong growth in the United States” to help reduce debt, Georgieva said.
“At the Fund, we believe that growth of course helps, but it cannot deliver fast enough the necessary adjustments. So, some (fiscal) measures would be necessary.”
The call for more action to reduce debt was echoed in the IMF’s Fiscal Monitor report on Wednesday, which warned that delays in an era of higher borrowing costs would only make the job harder in coming years.
While that message is a perennial one from the IMF, Rodrigo Valdes, the head of the IMF’s Fiscal Affairs department, said the surge in bond yields had left governments with little fiscal room to manoeuvre.
“We dialled up the urgency of our message,” he added.
BESSENT NO-SHOW
Bessent is not attending the annual meetings in Bangkok, despite this year’s US presidency of the Group of 20 major economies, instead favouring domestic engagements as the US midterm election campaign heats up.
He has acted as a chief spokesman for President Donald Trump’s economic policies, particularly touting the deep tax cuts passed last year by Republicans now trying to maintain control of the US Congress.
G20 finance ministers are due to meet on the sidelines of the Bangkok meetings on Thursday. The US has used its G20 presidency to try to rally allies to take stronger action to counter China’s “non-market” economic policies that have led to excess industrial capacity and a flood of global exports.
Asked about imbalances emanating from China, on a day when data showed it was on track to post a record trade surplus, Georgieva repeated longstanding advice to Beijing: “For surplus countries, what they need to do is increase domestic consumption. That clearly applies to China’s growth model. Shift from exports more toward domestic consumption.”
Deficit countries need to save more and spend less, while Europe needs to invest more in competitiveness, she said.
“To put it very simply, China needs to spend more, the US has to save more, and Europe has to invest more,” Georgieva added.
FRENCH FISCAL WORRIES
This week’s meetings have been dominated by worries about growing debt and rising bond yields and risks from the artificial intelligence boom.
France, one of the advanced economies worst hit by a global bond sell-off, needs to solve its own debt woes through fiscal consolidation, European Central Bank President Christine Lagarde said, effectively playing down speculation about an ECB intervention in the bond market.
Asked at a CNN event in Bangkok whether the ECB was about to help France, Lagarde said it was up to Paris to soothe investors’ nerves. “And for that one, the primary and first solution lies at home in France. And it has to do with fiscal policies,” she said.
The IMF has lauded Britain for taking steps toward consolidation, but made clear on Wednesday that it does not want London to accelerate the pace of fiscal consolidation. “Our recommendation is ‘stay the course’,” Valdes said.
Still, OECD Secretary-General Mathias Cormann called for “strong fiscal discipline” in a statement to the IMF’s steering committee, saying this was needed to ensure stability.
“In every G20 country except Germany and Türkiye, public debt as a share of GDP was higher in the first quarter of 2026 than at the end of 2007,” he wrote to the International Monetary and Financial Committee.
“Countries need to contain and reallocate spending, improve public-sector efficiency and make tax systems more effective. They should also protect investment that drives future growth, especially in education, skills and digital infrastructure.”
CALLS TO AID POOR COUNTRIES
Regarding the growing divergence between advanced countries benefiting from AI investment and those bypassed by it, highlighted in Tuesday’s IMF economic forecasts, Georgieva also urged IMF member countries to fully fund IMF facilities for low-income and vulnerable countries.
These include the Poverty Reduction and Growth Trust, which provides low- and zero-interest loans to low-income countries, and the Catastrophe Containment and Relief Trust, a fund that provides grants for debt-service relief and cancellation to the poorest and most vulnerable member countries, she said.
These countries, too, were being squeezed by higher bond yields, with average debt service costs that have increased to 14% of revenue from 6% a decade ago, even as overall debt burdens have eased, she said.
“The risk of divergence is most dangerous for those that are already further behind,” Georgieva added.
(Reporting by David Lawder and Andrea Shalal; Editing by John Mair, Shri Navaratnam, Toby Chopra)
Brought to you by www.srnnews.com
 Mexico to require digital platforms to protect minors from violent, sexual content
 US retirees to receive 3.6% Social Security increase in 2027
 US inflation heats up in September; Fed rate hike this month back on table